Over-Hedging and Under-Hedging: Risks for Businesses
By Harry Mills, Managing Director, Oku Markets · Updated
Over-hedging is when a business hedges more currency than it actually needs; under-hedging is when it hedges less than its real exposure. Both usually come from inaccurate forecasts, changes to the business or emotional calls on the market. Over-hedging brings close-out and rolling costs – under-hedging leaves your margins exposed to currency moves.
Key points
- A perfect hedge is rare – aim for a hedge ratio set out in your FX policy, not 100%.
- The usual culprits are forecasting errors, changes to suppliers, customers or tariffs, and decisions based on a market view.
- Leveraged products such as ratio forwards can leave you under-hedged or over-hedged – depending on where the market ends up.
- A written FX policy and regular checks against your forecasts keep your hedges in line.
In most circumstances, there isn’t really such a thing as a perfect hedge – especially when it comes to hedging the cash flows of future forecasts!
In this short article, I’ll look into the somewhat murky world of over- and under-hedging – in other words, hedging too much or too little.
Definitions
These are probably self-explanatory, but here goes…
Under-hedging: when a company’s hedging isn’t enough to protect it against adverse currency moves. That hedging might be natural – opposing currency cash flows from the normal course of business, such as matching revenues and costs in the same currency – or it might be derivatives contracts (forwards, swaps and options).
Over-hedging: the opposite – the hedged amount is greater than the underlying exposure.
The Most Obvious Causes…
The most obvious reason for over- or under-hedging is inaccurate forecasting.
Take a UK business that sells products into Europe, with monthly revenue of around €500K.
If the company hedges, say, €300K a month, you could argue it’s under-hedging – the total exposure hasn’t been hedged 1:1. I will add, though, that it’s often sensible to hedge below 100%, at whatever the right hedge ratio is for the company.
If it hedges €600K a month, it’s fairly plain to see that it’s over-hedging – and it’s likely the company won’t be able to deliver on those trades, so it could face close-out or rolling costs.
Beyond forecasting, economic and business changes can also throw hedging off course. Suppliers or customers moving (and so changing currency), government import/export tariffs, natural disasters and sanctions are all real-world examples.
Then there are people. We’re all prone to the odd poor, emotional or market-based decision, and that can leave a business with too much or too little cover. If the person making the FX decisions thinks the market will move in their favour, they might hedge less than usual – big mistake! Or perhaps they think they’re trading at the best opportunity and go big, hedging more (in volume and/or months forward) than their policy or hedge ratio dictates. Another big mistake.
Devastating Derivatives
“Derivative” isn’t a dirty word, and neither is “option”. But there’s a trend in the market – a proliferation of FX salespeople flogging complex currency options and “multi-leg” or “structured” option products.
Some of these products include a feature called leverage, where the protected amount is less than the amount you could be obliged to trade. Let’s look at the most basic leveraged option, the ratio forward:
- It’s like a traditional forward contract, but the protected amount is less than the obligated amount.
- It’s called a “ratio” forward because the contract has a protected:obligated ratio of, say, 1:2 or 1:1.5.
Here’s an example. A UK company buys products from the US in dollars. It enters a ratio forward to buy $100,000 a month at a rate of $1.2500, with a leverage ratio of 1:2.
If, on the expiry date, the market rate is lower (worse) than 1.2500, the company buys $100,000 at 1.2500. If the market rate is higher (better), it must buy $200,000 at 1.2500.
The ratio forward offers a more attractive protection rate than the equivalent forward contract – but from the outset, the company doesn’t know its cover – against a $200K need it’s 50% under-hedged, and against a $100K need it could end up hedged twice over by expiry.
So, using the example above, what happens if the company actually needed $100K – or $200K?
$100K exposure: the company is fully protected on the downside, but if the market rises, it must buy twice the dollars it needs, which means close-out losses or rolling costs. If the market goes to $1.30 and it sells the extra $100K, it loses roughly £3,077 (£80,000 to buy at 1.2500, ~£76,923 back when sold at 1.3000)!
$200K exposure: the company is only 50% protected. If the market falls, it has secured half at 1.2500 but must buy the other half at the spot rate – at a loss. If the market is above 1.2500, it delivers on the full amount.
A visual guide…
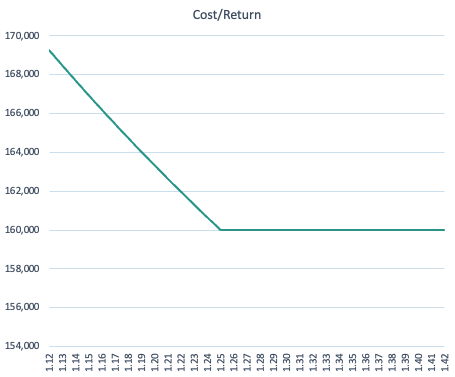 The chart below shows the total cost for a company that needs to buy $200,000 and took out the ratio forward above, at various GBPUSD spot rates.
When the spot rate is lower, the company buys $100,000 at 1.2500 and $100,000 at spot – a higher sterling cost, thanks to being 50% under-hedged.
Risks of Over- and Under-Hedging
Under-hedging:
- Losses from adverse currency moves
- Volatile profit margins and earnings
- Being forced to react, or to make market-based decisions
Over-hedging:
- Trading costs for rolling or extending hedges
- Losses from closing out out-of-the-money (OTM) positions
- Margin calls on excess positions that move OTM
- Reduced competitiveness from carrying unfavourable rates forward
- Fair value accounting losses on derivatives hitting earnings
How to Avoid Over- and Under-Hedging
It’s very easy for a business to end up with too much or too little hedging against its real currency exposure. Bad decisions, inaccurate forecasts and business changes are the main culprits – but speculative or leveraged derivatives are increasingly a big factor too.
The perfect hedge is an elusive thing. Here’s a brief recap of what we’ve covered, and what you can do about it.
Key Takeaways
- Inaccurate forecasting: gaps between forecast and actual cash flows leave hedges too big or too small. This is about forecasting your underlying exposure – not predicting exchange rates.
- Economic and business changes: moving suppliers or customers, government policy, natural disasters and sanctions can all knock a hedging strategy off course. Stay agile.
- Emotional or market-driven decisions: trying to time the market rarely ends well. Base hedging decisions on a clear strategy, not sentiment.
- Derivatives and leveraged options: products like ratio forwards can look attractive, but they add complexity. Understand them properly before they go anywhere near your risk management strategy.
Taking Action
- Professional guidance: our FX risk-management service can help you assess your exposures and build a hedging strategy that fits.
- Risk assessment: check your currency exposure regularly, and make sure it matches your business objectives and what you can afford.
- Policy and strategy: set a clear FX policy that reflects your business’s needs and risk tolerance.
- Education and training: make sure your team understands your currency risk and the hedges in place – it’s the cheapest way to avoid costly mistakes.
- Review and adapt: currency markets move, and so does your business. Review your hedges against actual cash flows regularly.
There’s no one-size-fits-all answer – every business is different, and the right approach depends on your circumstances.
If you’re unsure whether your hedge ratios are right, get in touch – we’re always happy to take a look. Call us on +44 (0) 203 838 0250 or write to info@okumarkets.com.
For related decisions, explore hedge amounts and time horizons, programme selection and measuring residual FX risk.
Frequently Asked Questions
1. What is currency risk management, and why is it important for businesses?
Currency risk management involves strategies and tools used by businesses to protect themselves from the adverse effects of currency exchange rate fluctuations. It’s important because currency movements can impact a company’s profitability and financial stability, especially for those engaged in international trade.
2. What is over-hedging and under-hedging in currency risk management?
- Over-hedging: this occurs when the hedged amount exceeds the underlying currency exposure.
- Under-hedging: this leaves some currency exposure unprotected. A hedge ratio below 100% can be an intentional, appropriate policy choice if the remaining risk is understood and tolerable.
3. What are the common causes of over- and under-hedging?
Over- and under-hedging often result from differences between forecast and actual currency cash flows, including changes in the amount or timing of receipts and payments.
Economic and business changes, such as shifts in supplier/customer locations, government policies, or natural disasters, can also disrupt hedging activities.
Emotional or market-driven decisions, like trying to time the market or acting on sentiment, can lead to suboptimal hedging positions.
4. What are leveraged options, and how do they relate to FX risk management?
Leveraged options, such as ratio forwards, are financial instruments that provide a lower protected amount than the potential obligated amount. They offer unique benefits but introduce complexities. In the context of currency risk management, understanding these instruments is crucial before incorporating them into your strategy – financial losses and mark-to-market losses can be greater with these products when compared to the equivalent forward contract alternative.
5. What are the risks associated with under-hedging and over-hedging?
- Under-hedging risks: this can lead to financial losses due to adverse currency movements, profit margin and earnings volatility, and forced market-based decisions.
- Over-hedging risks: trading costs, losses from closing out out-of-the-money positions, margin calls, reduced competitiveness, and fair value accounting losses (of derivatives) impacting earnings are potential risks.
6. How can businesses mitigate the risks of over- and under-hedging?
- Seek professional guidance from experts in currency risk management.
- Regularly assess currency risk exposure to ensure it aligns with business objectives.
- Establish clear currency risk management policies and strategies.
- Educate and train your team about currency risk and hedging strategies.
- Continuously review and adapt hedging positions to changing circumstances.
- Consider diversifying your risk management tools.
7. Is there a one-size-fits-all solution for currency risk management?
No, there’s no one-size-fits-all solution. Each business is unique, and the optimal approach will depend on specific circumstances. Tailor your currency risk management strategy to align with your business needs and risk tolerance.
8. Where can businesses find expert advice on currency risk management?
You can seek expert advice from financial institutions, currency risk management consultants, or professionals experienced in international finance and currency markets. Oku Markets can provide such expert guidance and support.
9. What is a hedge ratio? (new)
It’s the share of your currency exposure that you’ve hedged – €300K hedged against €500K of monthly revenue is a 60% hedge ratio. Most businesses set a target ratio, or a range, in their FX policy rather than aiming for 100%.
10. What happens if I hedge more than I end up needing? (new)
You still have to settle the extra – either take delivery of currency you don’t need, roll the contract forward or close it out at the market rate. If the market has moved against you, that means a loss on the surplus, and possibly a margin call before then.
11. How often should a business review its hedges? (new)
At least every time your forecasts change, and as a routine every month or quarter. Compare the hedges in place against your latest cash-flow forecast and actual receipts and payments – then top up, trim or roll as your FX policy allows.