Mark-to-Market & Margin Calls
By Harry Mills, Managing Director, Oku Markets · Updated
A margin call is a request to add cash collateral to an open currency hedge when its mark-to-market value moves against you. Mark-to-market is the ongoing valuation of that hedge at current rates. Most hedges need an initial margin – a small percentage of the trade, say 3% – and losses beyond it trigger a call for variation margin.
Key points
- A currency hedge such as a forward contract changes in value as the spot rate moves – this is its mark-to-market (MTM) valuation.
- Opening a hedge usually means holding cash collateral, the initial margin, typically a small percentage of the trade size (say 3%).
- If the position’s value falls below the margin held (or the credit limit), you’ll be asked for variation margin – a margin call.
- Subject to a credit assessment, a credit facility can mean you may not need to post initial margin.
4-minute read
Nobody likes receiving a margin call, especially when it’s a surprise. In this article we’ll explain the basics of mark-to-market valuations, how collateral is used for currency hedges, and of course, margin calls…
Enter the Derivative
When a company enters a currency transaction to manage its foreign exchange risk, it takes a position in the underlying currency pair to offset losses induced by adverse movements in the exchange rate.
Example
- A UK boatbuilder has sold a yacht to a customer in Ireland for 1 million euros
- They expect to receive £870K on conversion, meaning an exchange rate of 1.1494
- The sale completes in 3 months, so they book a forward contract to sell €1m
- If the pound appreciates against the euro, from 1.15 to 1.20, the sale price of €1m would return £833k, but this is offset by the forward contract which is “in the money”
New to forwards? Our guide to what an FX forward contract is covers the basics.
Mark to Market & Margin
Entering the forward contract to mitigate currency risk isn’t where the story ends. The FX position changes in value over time – chiefly, as the spot rate moves – and, whilst this offsets the underlying transaction (the yacht sale), until the exchange of funds occurs, the hedge itself brings about a specific cash flow risk.
When a company enters a currency hedge, there’s typically a need to hold cash collateral with the bank/broker. This is called the initial margin and it’s usually equivalent to a small percentage of the total trade size, say 3%. Sometimes the initial margin is waived because a credit limit is provided to the firm by the bank/broker.
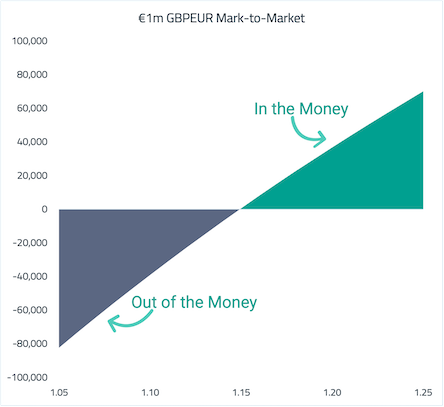
As the underlying exchange rate moves, the value of the position (the currency hedge) changes. A rule of thumb is that if the spot rate moves in what would be a favourable direction (spot is ‘better’ than the hedged rate), the hedge is worth less than at the time of booking – it’s Out of the Money.
- In the Money (ITM): hedge is worth more than at the time of booking
- At the Money (ATM): hedge is worth the same as at the time of booking
- Out of the Money (OTM): hedge is worth less than at the time of booking
Here we see a Mark-to-Market chart for the €1m (EUR sell / GBP buy) forward contract that our example boatbuilder entered:
Margin Call
If the value of the open position moves negative, meaning it would cost more to exit the trade than the initial margin that is held (or greater than the credit limit), the company will need to increase the collateral balance by adding additional variation margin. This process is known as a margin call.
The process of monitoring open positions and producing the prevailing valuation is known as marking to market, and the position value should be provided online.
The bigger the hedge relative to the real exposure, the bigger the swings – and the margin calls – can be. Our piece on over-hedging and under-hedging explains why sizing matters.
Credit Facilities for Hedging
Margin doesn’t have to mean tying up cash. Subject to a credit assessment, clients may not need to post initial margin – the credit facility stands in its place. Ask us for more details if this is of interest to you!
Want to know more?
Our philosophy at Oku Markets means no smoke and mirrors, and complete transparency with pricing and how markets operate.
We give live position value and collateral management via our online platform, so you can always manage your positions and there will never be any surprises!
You can find out more about how we approach hedging on our risk management page, or contact us for a review of your currency processes and for our guidance and suggestions at info@okumarkets.com or 0203 838 0250.
Frequently Asked Questions
What does mark-to-market mean for a currency hedge?
Mark-to-market is the process of valuing an open position at current market rates. For a forward contract, it shows what the hedge would be worth (or cost) if you closed it out today.
What is initial margin?
Initial margin is the cash collateral held with your bank or broker when you open a currency hedge. It’s usually a small percentage of the total trade size, say 3%.
What is variation margin?
Variation margin is the extra collateral you’re asked to add when the value of your open position moves negative by more than the initial margin held (or your credit limit).
What is a margin call?
A margin call is a request from your bank or broker to top up your collateral with variation margin because your hedge has moved out of the money by more than the initial margin held (or your credit limit).
Does a margin call mean my hedge has failed?
No. If spot moves in what would be a favourable direction, the hedge loses value – but the underlying transaction gains, so the two offset each other. The margin call is a cash flow issue, not a loss on the overall position.
Do I always have to post initial margin?
Not always. Subject to a credit assessment, clients may not need to post initial margin if they’re given a credit facility.
How do I know when a margin call might be coming?
Keep an eye on the live value of your positions. At Oku Markets, position values and collateral are available via our online platform, so there are no surprises.
Thanks for reading 👋